
Anthropic is the most anticipated IPO of the year, and the largest on record. It priced at $83 a share on November 18, above its marketed range of $70 to $78, raising $81.3 billion and valuing the company at roughly $1.5 trillion. Shares began trading on the Nasdaq Global Select Market on November 19 under the ticker ANT.
Before the first trade, perpetual futures tracking Anthropic’s pre-IPO shares were already changing hands on Hyperliquid, the crypto venue open to investors outside the United States, where the contract ran near $96.93 and implied a valuation closer to $1.7 trillion, a 24% jump on the top of the range. The numbers backing up these predictions are highly dubious, but the novelty of the industry and its rocket-powered growth give ample ammunition to market bulls.
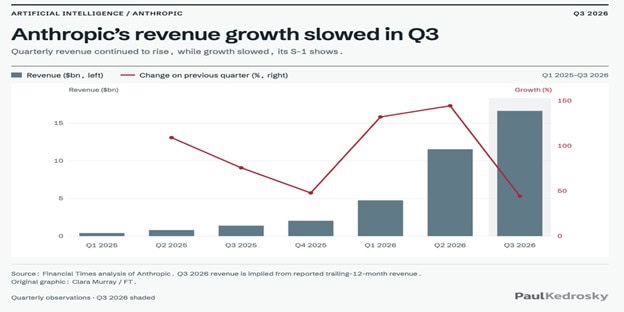
However, the annual and quarterly growth of Anthropic is like nothing ever seen before. In the first three quarters of 2026, Anthropic’s revenue reached $33.2 billion, up 1,200% over the same period last year.
NYU Stern School of Business professor Arun Sundararajan said in an interview: “There’s no real historical analogy for a company that has been this successful this fast.”
The Deceleration Nobody Priced In
That doesn’t mean it will continue. Anthropic’s growth slowed in the third quarter of 2026, with sequential revenue growth falling from roughly 140% to about 45%. Paul Kedrosky reads that as an early sign that the coding era is ending, while allowing that it is too soon to tell whether the trend holds. The exposure is structural.
About 80% of Anthropic’s first-half revenue came from usage-based customers paying through the API, which leaves the top line at the mercy of token prices. Now, AI companies are in a transition from early adopters who barely glanced at price to more cost-sensitive customers, which could put headwinds on that rapid growth we saw heretofore.
Despite this, sales have not slowed, with big-ticket customers who spend upwards of 100 grand growing from about 1,500 in December 2025 to more than 11,900 as of September 30, 2026. More than 1,900 of those customers now spend at least $1 million a year, and roughly 250 spend $10 million or more.
Matt DiLallo, writing in an investor outlet, said that although the company is exceptional, he would not pay $83 for the stock. His base case puts the shares at $91 in 2031, an annual return of about 2%. To clear the 10% a year he wants, he would have to buy near $56.
The Bill Comes Due Before the Growth Does
Part of the reason is spending. The company has committed to $895.4 billion of spending on compute and infrastructure in multi-year agreements and leases, with roughly $69.8 billion of it payable within twelve months. Over the next few years, Anthropic’s ravenous need for capital will likely eat into profits.
Michael Ewens, the David L. and Elsie M. Dodd Professor of Finance at Columbia Business School, noted that companies “tend to go public at the peak of their growth,” and that it rarely lasts.
That said, he expects Anthropic to grow much faster than the economy, perhaps 40% to 60% a year, which is nothing to sneeze at. The rate it would take to reward investors at the price being asked is another matter.
Shivaram Rajgopal, the Roy Bernard Kester and T.W. Byrnes Professor of Accounting and Auditing at Columbia, estimates that at a $2 trillion valuation, Anthropic’s profits would need to grow between 36% and 76% a year for five years to deliver a return to investors.
No company of that size has ever sustained more than 35% annual growth across five years. Even the floor of Rajgopal’s range would set a record.
And yet, Anthropic’s projections for its growth are ambitious, to say the least. Reports estimate a forecast of $190 billion to $200 billion in revenue for 2028, measured against an annualized run rate of $81 billion as of October 31.
That is close to two and a half times the business in two years. This leaves no wiggle room for a company already seeing slower growth.
The Record Everyone Is Counting On
Strip away the ticker and the crypto side bets, and one question is left. Anthropic has built the fastest-scaling business anyone has put on paper, and it has signed contracts that assume the scaling never stops.
The $895.4 billion in compute commitments binds the company whether or not the revenue arrives, and nearly $70 billion of it falls due inside a year. The revenue meant to service it is a projection, and that projection already missed its own slope in the third quarter.
That is the trade on offer at $83. The price assumes a growth rate no company Anthropic’s size has ever held, sustained for five years, resting on a customer base drifting toward buyers who watch the meter.
The two Columbia professors who ran the numbers arrived at the same place from opposite directions. Ewens expects the company to outgrow the economy and still puts the peak behind the filing. Rajgopal can reach a return, but only across a record nobody has set.
None of this makes Anthropic a weak company. It makes $83 a wager that the past two years were the start of the curve rather than its crest.
Author: Tim Tolka, Senior Reporter
#Crypto #Blockchain #DigitalAssets #DeFi
The editorial team at #DisruptionBanking has taken all precautions to ensure that no persons or organizations have been adversely affected or offered any sort of financial advice in this article. This article is most definitely not financial advice.
See Also:
SpaceX IPO at $1.77 Trillion: Most Important Since Aramco, or Most Overvalued? | Disruption Banking
Is the 2026 IPO Boom Hiding Weak Aftermarkets? | Disruption Banking

Tim Tolka
Tim Tolka, Senior Reporter at Disruption Banking, covers digital assets, monetary policy and the politics of global finance. Based in Mexico City, he brings an investigative edge to his reporting, informed by a Master's in International Affairs and his work as an author and screenwriter.