
One of the longest-running British blockchain businesses has been Blockchain.com. The company opened U.S. operations in 2021 and has spent the past year concentrating those efforts in Dallas.
It has two co-CEOs because leadership is split by geography and function. Peter Smith, a founder, stays in London and focuses on product, engineering, and technical strategy. Lane Kasselman, a longtime executive who previously ran business operations, is based in Dallas and handles commercial operations, capital markets, and the U.S. business.
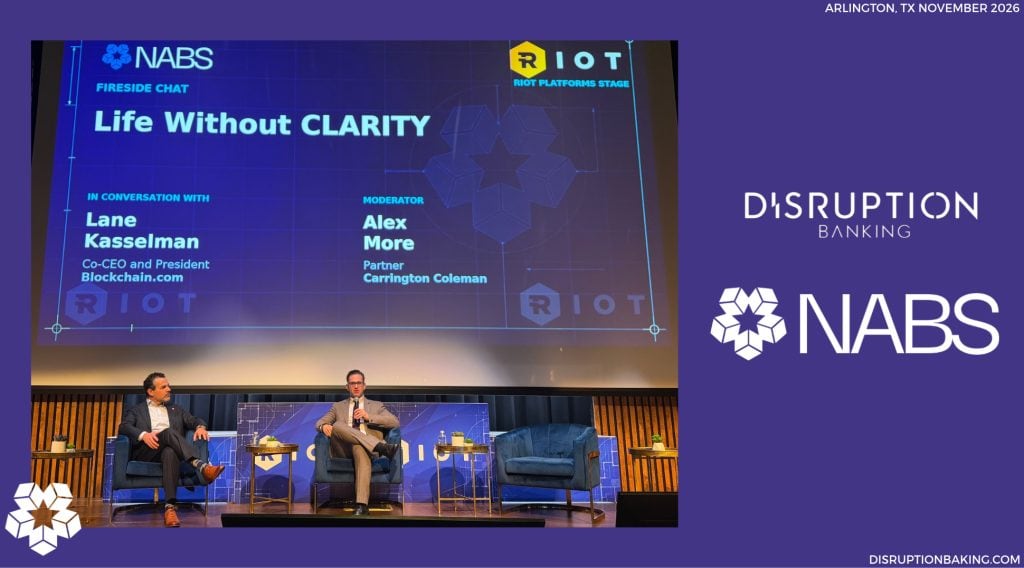
On the second day of the North American Blockchain Summit, Kasselman sat down with Alex More, a partner at Carrington Coleman and one of the sharper crypto lawyers in Texas. The two were there to discuss “Life without Clarity.” They covered more than that.
Kasselman and More discussed the outlook on stage at the summit:
Most bills that pass through Congress are not very complicated. The Clarity Act was a little different. https://t.co/1EUPRiO6jz's President and Co-CEO @kasselman sat down with Alex More of Carrington Coleman to discuss "Life After Clarity" at the North American Blockchain Summit… pic.twitter.com/w8tlckZmmt
— Digital Startup (@digitalstartup5) November 19, 2026
What the Clarity Act Was Supposed to Fix
More opened by asking what the Clarity Act was supposed to achieve. Kasselman said the core question had been which federal agency should regulate the industry. “For a long time, there were no clear rules in the U.S.,” he said. The debate centered on whether the SEC or the CFTC should take the lead, because “the regulations that come with that agency differ materially.” He described most major policy bills as relatively simple in their original aim. Clarity started that way, then picked up additional provisions as it moved through Congress. “That was the central initiative we were trying to get an answer to,” he said. In his view, the industry already has more practical guidance today than it did a few years ago, even without the bill.
When asked why the legislation failed, Kasselman pointed to two near-misses in the past year. One involved friction between Coinbase and the banking industry. The other, he said, came down to an 11th-hour addition restricting the executive branch from engaging in certain crypto activities. That provision was not part of the original intent and is where the effort stalled.
How Policy Actually Gets Made: Lessons from San Francisco
Kasselman then turned to how policy usually develops. He previously worked in the office of then-San Francisco Mayor Gavin Newsom from roughly 2004 to 2007 as Deputy Policy Director. While there, the office tried to legalize cannabis outright in the city. Progressives and liberals in San Francisco could not agree, and the effort failed. They went back to the drawing board and advanced a narrower medical-cannabis dispensary model that both sides could support. That version passed and later influenced policy elsewhere. He used the episode to illustrate that regulation is iterative: early versions fail, then get adjusted until something workable appears. He expects the same with crypto legislation. The next version, he said, will likely look different and may not even be called Clarity.
He also noted that the current Congress was elected with a two-to-one ratio of crypto-supportive members over opponents, calling it “the most crypto-friendly Congress in history.” That, in his view, reduces the risk that a change in control will kill progress outright.
Why Crypto Is in a Stronger Position in the US Than It Looks
Blockchain.com is one of the longest-running crypto platforms in the world. The U.S. now accounts for about a third of the company’s website traffic. The firm is also planning an IPO in the U.S., having filed confidentially with the SEC earlier this year. In September, Blockchain.com teamed up with the New York Stock Exchange to explore 24/7/365 access to tokenized U.S. stocks and ETFs.
These moves will help increase the company’s visibility in the U.S. Kasselman argued that the industry is already in a relatively strong position even without the Clarity Act. “The reality is, we’re in a very good place in the U.S. right now,” he said. He pointed to 32 rulemaking procedures at the SEC and CFTC that have been started, completed, or are still in process, covering tokenization and digital assets. Because rulemaking takes years to create and years to unwind, he said the current environment provides practical clarity for the near term. “Even in the event that we have another administration in a couple of years, and then somehow the people in that administration were very anti-crypto, it would take them several years to unwind what has been done today,” he said. “I feel like we’re in a very good spot right now.”
He added that his co-CEO sits on the CFTC Innovation Advisory Committee and that the company spends considerable time with both agencies on issues such as public-company disclosure rules that no longer fit crypto businesses well. He contrasted the U.S. situation with permanent frameworks elsewhere. The EU has MiCA, the UK has FCA registration, and countries such as Nigeria and Ghana already have rules in place. “They don’t really care what’s happening in the U.S. related to crypto,” he said. “They know we’ll eventually get there.” For now, he said, the U.S. is catching up with regulation rather than leading.
State Money Transmitter Licenses Still Create Friction
Kasselman described the state-by-state process as cumbersome. Roughly 30 states have money-transmitter licenses that crypto firms can obtain; others are still writing rules. California’s bit-license regime is scheduled to take effect next year, and companies are already applying. “It is frustrating that we have to work through the MTL process, bit license process across every single state,” he said. “I don’t think that’s sustainable for the long term.” He noted that the federal government has recognized the problem, which is why firms are pursuing new federal licenses that would allow broader operation. At the same time, states retain authority over how consumers interact with funds, so state-level compliance is unlikely to disappear. “It would just be nice if they all had consistency in their rules,” he added.
He singled out Texas as still catching up. “Dealing with the Department of Banking can be quite challenging compared to dealing with… their counterparts in other similar states,” he said. Florida, he added, has been easier to work with on money-transmitter licensing and has a deeper understanding of crypto. He expects Texas to reach parity over time. More added that states function as laboratories of innovation and that the industry should continue to use them while federal rules remain incomplete.
What Happens Next Without a Clarity Act
Kasselman said one under-discussed consequence of Clarity’s failure was that several large traditional-finance firms paused or abandoned plans to acquire crypto companies. Rumors had circulated that firms including JPMorgan and Charles Schwab were exploring deals; those conversations largely dried up. “That’s good news for me,” he said. “It means I don’t have a behemoth trying to compete with me.” He also noted that the last venture cycle produced few new crypto competitors, so the field remains dominated by companies that have been operating for a decade or more.
His hope for the next year is that more of the remaining private crypto firms go public, that there is clearer agreement that either the SEC or the CFTC is the primary federal regulator, and that NYSE or Nasdaq begins tokenization efforts (starting, he suggested, with bonds rather than equities). If those things happen, he said, the industry’s place in the broader economy will be more firmly established.
On the question of catching up after years of uncertainty, Kasselman pointed to the concentration of major financial institutions in the United States and the ongoing convergence between crypto and traditional finance. “I think the U.S. will reclaim its place as the crypto leader in the world,” he said. He acknowledged that consumer access and compliant product offerings still vary by state, but he expects that to change because more institutions and consumers are already holding or offering crypto.
The panel closed with audience questions. On tokenized stocks, Kasselman noted that some products are already available through platforms such as Robinhood and Ondo, but that broad access through the major exchanges will take time. “I think we’ll probably see NYSE and Nasdaq do something within the next 12 months,” he said, “but it’s not going to be like you can go buy AT&T stock on NYSE in January.” Broader access through the major exchanges, he said, will take time — much like the path to federal legislation.
Author: Andy Samu
See Also:
Which Stablecoins Will Win? Non-Bank or Bank Issued? | Disruption Banking
Why is Coinbase leaving Delaware for Texas? | Disruption Banking

Andrew Samu
Andrew Samu, Editor-at-Large at Disruption Banking, shapes the publication’s global coverage of banking, capital markets and digital assets. Based at London’s Level39, he combines market analysis with a strong commercial perspective, informed in part by his role as Commercial Director at Verita HR.