
Banks are investing in faster ways to move money, but multinational businesses can still find their cash trapped between financial institutions.
At the Singapore FinTech Festival 2026, Humphrey Valenbreder, CEO of institutional settlement network Partior, questioned whether speed was really the biggest problem facing corporate treasurers. For businesses holding money across several banks and markets, accessing that liquidity remains a more complicated challenge.
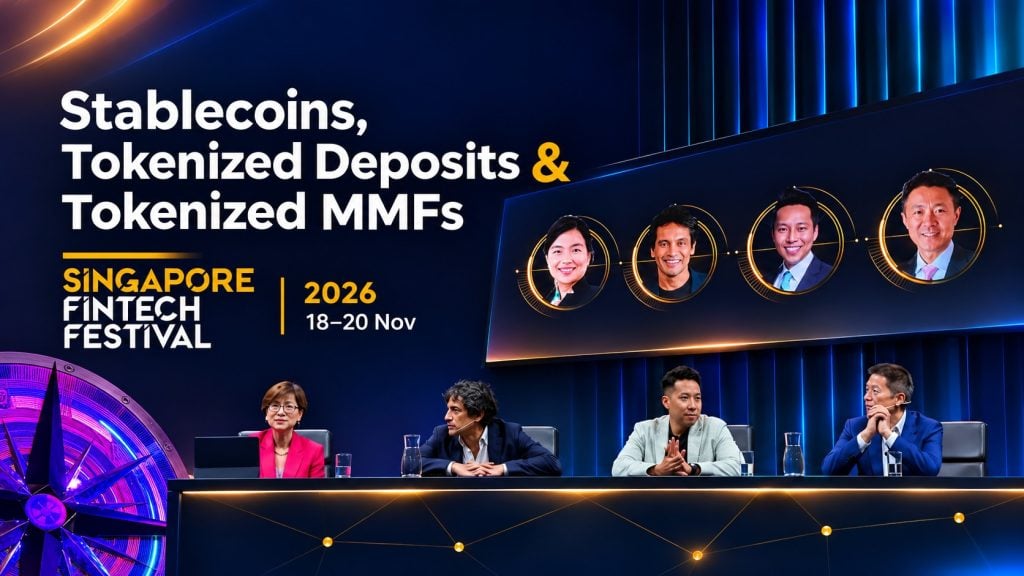
The argument emerged during a November 19 discussion with HSBC and Paxos on the future of stablecoins, tokenised deposits and tokenised money market funds. Moderated by Laura Loh of Temasek, the panel explored which instruments were commercially useful and whether institutions could make them work together.
Where Stablecoins Make Commercial Sense
Khairi Azmi, Head of APAC at Paxos, argued that stablecoins could have their greatest impact on business payments, particularly those settled in US dollars.
“Stablecoin is going to make the biggest impact,” he said, referring specifically to the B2B market.
Retail payments, Azmi suggested, already work remarkably well in many markets. Consumers can use QR codes and credit cards domestically and overseas without needing an entirely new payment instrument.
For businesses, however, the opportunities are a little bit different. Azmi identified cryptocurrency exchanges, asset managers and payment service providers among the potential beneficiaries of stablecoin settlement.
The attraction is based in the ability to move dollar-denominated value outside conventional banking hours, potentially reducing delays and transaction costs. Yet, those advantages still depend on what happens at either end of the payment.
Azmi acknowledged that digital wallets, gas fees and moving funds between wallets can introduce more complexity to the process. Specialist providers could make stablecoin transactions more accessible by managing these processes for institutional clients.
A stablecoin may transfer quickly on a blockchain, but the recipient could still face delays converting it into money held in a conventional bank account.
The question of whether banks or non-bank issuers are better placed to serve these markets was also debated at the North American Blockchain Summit this week. There, banking and digital asset executives examined whether the two models would compete or coexist.
In Singapore, the discussion focused a little more on how institutions could use these different forms of money across their existing financial relationships.
HSBC Expands Tokenised Deposits to Eight Markets
Lewis Sun, Managing Director and Global Head of Digital Currencies at HSBC, told the panel that the bank’s tokenised deposit services were now live in eight markets, compared with four when he spoke about them last year.
“We have gone live with tokenised deposit services in eight markets,” Sun told the audience here at SFF 2026.
He explained that tokenised deposits offered banks a familiar approach to digital money, retaining established banking principles and compliance arrangements while allowing corporate treasurers to transfer funds between locations around the clock.
HSBC also announced a successful pilot with Uber in October, showing how corporate treasurers could use tokenised deposits to purchase and redeem tokenised money market funds, including outside conventional market hours.
For treasury teams managing surplus cash, earning a return can be just as important as accessing funds quickly. Tokenised money market funds offer exposure to investment portfolios, while tokenised deposits remain claims on commercial banks.
Sun also pointed to HSBC’s involvement in stablecoins. On October 23, the bank announced the launch of RedCoin, a Hong Kong dollar stablecoin under the Hong Kong Monetary Authority’s regulatory framework.
The bank’s work across tokenised deposits, money market funds and stablecoins reflects the different requirements of corporate payments, liquidity management and short-term investment.
Partior Questions Whether Faster Settlement Is Enough
Valenbreder approached the question from the perspective of a settlement infrastructure provider.
“I always wanted to be a consultant, but I never got a job there,” he joked, before offering what he described as the familiar consultant’s answer: it depends.
For Valenbreder, the starting point was identifying the problem institutions were actually trying to solve.
“It’s really trapped liquidity that we’re trying to solve for on the corporate and institutional side,” he argued.
Multinational corporate treasurers already manage cash forecasting, accounts payable and receivables through existing systems, however challenging they may be. Improving transaction speed alone may therefore offer less value than making liquidity available across different financial institutions.
Valenbreder questioned whether stablecoins would become a feasible alternative for institutional interbank settlement in the short term, particularly when many digital money arrangements still operate within closed networks.
A tokenised deposit might move efficiently between accounts at one bank, but the benefits become more limited when a business holds funds across several institutions operating on separate systems.
Stablecoins face similar challenges when counterparties operate across incompatible networks or lack access to suitable redemption services.
On November 16, DBS and Kinexys by J.P. Morgan announced a service connecting their tokenised deposit networks, allowing institutional clients to transfer US dollars between Singapore and the United States around the clock. Partior provides settlement orchestration for the service, with Ant International named as its inaugural client.
The connection demonstrates how separate banking networks can work together, although the service currently covers two institutions and one currency. The announcement did not provide a figure for how much liquidity the arrangement could release or how much participating institutions might save.
Connecting networks is becoming possible. Whether those connections can reduce funding costs and improve the deployment of corporate cash at scale remains to be demonstrated.
Which Form of Money Would Institutions Actually Choose?
Loh tested the speakers’ arguments with three scenarios, asking the audience to choose between stablecoins, tokenised deposits, tokenised money market funds and conventional fiat money.
For payroll, the audience favoured conventional bank payments over tokenised alternatives.
The second scenario involved a company holding $50 million that it would not need for 90 days. This time, tokenised money market funds attracted support.
Sun acknowledged that the question naturally favoured money market funds, given the importance of earning a return on idle cash.
The final scenario involved settling a US-dollar payment to a supplier in Singapore that evening.
“Again, I think it depends,” Valenbreder responded.
The appropriate instrument, he explained, would depend on the payment amount, where the money was held and whether the buyer and supplier used the same bank.
Stablecoins could be useful for certain international payments, tokenised deposits could support transfers within banking networks, and tokenised money market funds could provide a way to invest surplus liquidity. None offered an obvious answer to every scenario.
When asked what would accelerate adoption, Azmi pointed to interoperability across jurisdictions, while Sun emphasised common standards connecting digital money, digital assets and traditional payment infrastructure. Valenbreder also added that institutions would need effective orchestration to ensure that connecting these systems did not increase the risk of transactions breaking down.
The panel ended without choosing a clear winner.
Banks are beginning to connect their tokenised deposit networks, while stablecoins offer another way to move money across borders. But faster payments do not necessarily solve the problem of cash being tied up across different banks and markets.
For corporate treasurers, the priority is making that money easier to access, not simply moving it faster.
Author: Grace Sharp
See Also:
Which Stablecoins Will Win? Non-Bank or Bank Issued?
DBS and JPMorgan Link Tokenized Deposit Networks for 24/7 Dollar Transfers
Singapore FinTech Festival 2026 Opens as Global Finance Faces a Period of Rewiring